Health insurance terms such as deductible, copay, coinsurance, and out-of-network benefits can make it difficult to understand what you will pay for healthcare. If you are considering occupational therapy or mental health services, understanding these terms can help you plan for costs and make an informed decision about care.
New Horizons Wellness Services (NHWS) is an out-of-network, private-pay provider. We do not directly bill commercial insurance companies. However, depending on your insurance plan, you may be eligible to receive partial reimbursement for some services.
This guide explains common health insurance terms, how out-of-network benefits work, and what to ask your insurance company before starting services at NHWS.
Health Insurance Costs: What Do the Terms Mean?
What is a health insurance premium?
A premium is the amount you pay to maintain your health insurance coverage, usually every month. You pay this amount whether or not you use healthcare services.
Your premium is separate from your deductible, copays, and coinsurance.
What is a deductible?
A deductible is the amount you must pay toward eligible healthcare expenses before your insurance plan begins paying its share of services subject to the deductible.
For example, if your deductible is $1,000, you may need to pay $1,000 in eligible expenses before your plan begins contributing toward covered services.
Some plans have separate deductibles for in-network and out-of-network care. Ask your insurer which deductible applies to services from an out-of-network occupational therapist or mental health provider.
What is coinsurance?
Coinsurance is the percentage of an eligible healthcare expense that you are responsible for paying.
For example, if your plan covers an out-of-network service at 60% of its allowed amount after you meet your deductible, the plan may pay 60% and you may owe the remaining 40%, subject to your plan’s rules. Coinsurance is generally calculated using your insurer’s allowed amount, not necessarily the provider’s full fee.
What is a copay?
A copayment, or copay, is a fixed amount you pay for a covered healthcare service. For example, your plan might require a $30 copay for a particular visit. Some plans have different copays for in-network and out-of-network services.
What is an out-of-pocket maximum?
An out-of-pocket maximum is the limit on what you pay toward certain covered healthcare expenses during a plan year.
Do not assume that every payment to an out-of-network provider counts toward this limit. Depending on your plan, out-of-network expenses, charges above the allowed amount, and noncovered services may not count.
Ask your insurer whether out-of-network occupational therapy or mental health expenses count toward a separate out-of-network maximum.
What is an allowed amount?
The allowed amount is the amount your insurance plan recognizes for a covered service when calculating its payment. It may also be called the eligible expense, payment allowance, or negotiated rate. Your insurer generally calculates any reimbursement using the applicable allowed amount and your plan’s benefit rules.
What are out-of-pocket costs?
Out-of-pocket costs are expenses you pay yourself. They may include deductibles, copays, coinsurance, and charges for services your plan does not cover.
When considering out-of-network therapy, include the provider’s full fee in your budget unless your insurer has confirmed how much it may reimburse.
Understanding Health Insurance Plan Types
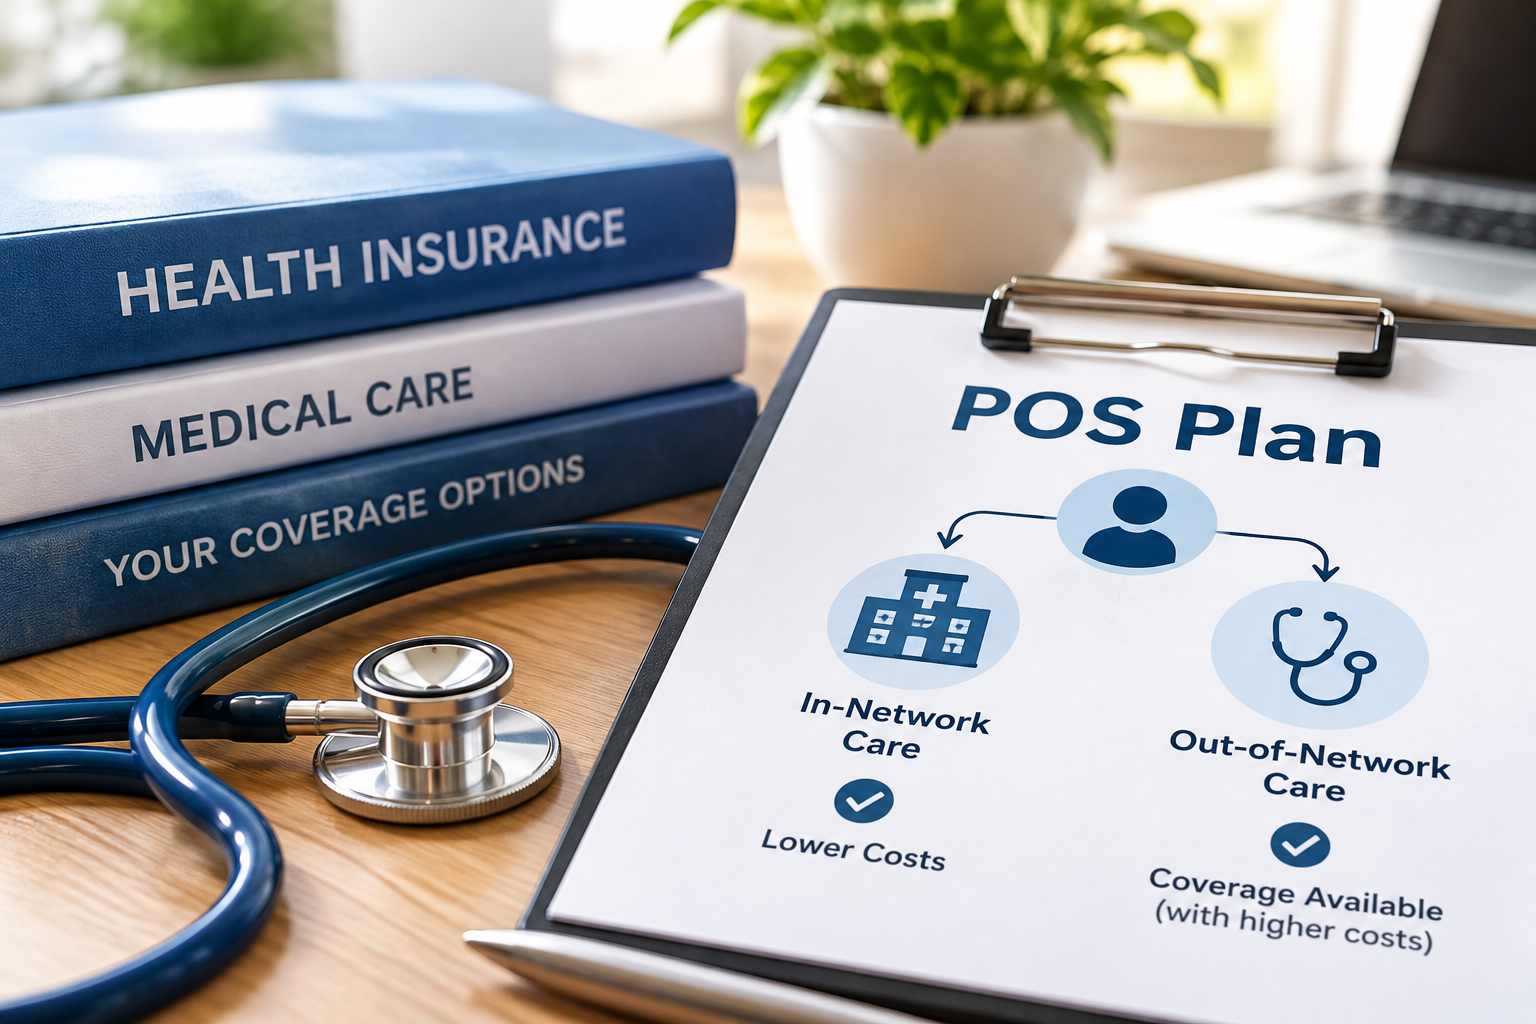
Your plan type affects whether you can receive benefits for services from an out-of-network provider.
What is an HMO?
An HMO, or Health Maintenance Organization, generally limits coverage to providers in its network, except in certain circumstances such as emergencies. Referrals may also be required..
What is a PPO?
A PPO, or Preferred Provider Organization, generally offers access to both in-network and out-of-network providers.
Some PPO plans provide reimbursement for eligible out-of-network occupational therapy or mental health services. However, out-of-network deductibles, coinsurance, and other requirements may apply.
What is an EPO?
An EPO, or Exclusive Provider Organization, generally limits coverage to its provider network, except in certain circumstances such as emergencies. Referrals are not usually required for specialist visits.
What is a POS plan?
A POS, or Point-of-Service plan, combines features of HMO and PPO plans. It may allow out-of-network care under certain conditions, but referrals or other requirements may apply.Accounts That Help You Save for Care
Accounts That Help You Save for Care
What Is an HSA?
A Health Savings Account lets you set aside pre-tax money for future medical expenses. To qualify for an HSA, you must be enrolled in a high-deductible health plan. Unused funds roll over year to year and stay with you even if you change jobs or insurers.
What Is an HRA?
A Health Reimbursement Arrangement is an employer-funded account that reimburses employees for qualifying out-of-pocket medical expenses. Unlike an HSA, an HRA is funded entirely by the employer, not through employee payroll deductions, and typically doesn’t carry over between jobs.
What Is an FSA?
A Flexible Spending Account is another pre-tax account for medical expenses, but unlike an HSA, FSA funds generally must be used within the plan year or a short grace period, or they’re forfeited. FSAs don’t require a high-deductible plan to qualify.
What Does Out-of-Network Mean for Occupational Therapy or Counseling?
What is an out-of-network provider?
An out-of-network provider is a healthcare professional who does not have a contract with your insurance plan.
New Horizons Wellness Services is an out-of-network provider. We use a private-pay model, which means clients pay NHWS directly for services rather than having us bill their commercial insurance company.
Depending on your plan, you may be able to submit documentation to your insurer and request reimbursement for eligible services.
What are out-of-network benefits?
Out-of-network benefits are the provisions in an insurance plan that may cover some costs for services received from providers outside the plan’s network.
These benefits vary by plan. Your insurer may require you to meet a separate deductible, obtain prior authorization, or submit specific documentation.
Before starting care, ask your insurer whether your plan includes out-of-network benefits for the exact service you are considering.
What is a superbill?
A superbill is an itemized document that contains information your insurer may need to process a reimbursement request. It typically includes information such as the date of service, service codes, provider information, and other required claim details.
NHWS can provide a superbill for you to submit to your insurance company for possible reimbursement.
A superbill is not a guarantee of payment. Your insurer determines whether the service is eligible and how much your plan will reimburse.
What is a reimbursement claim?
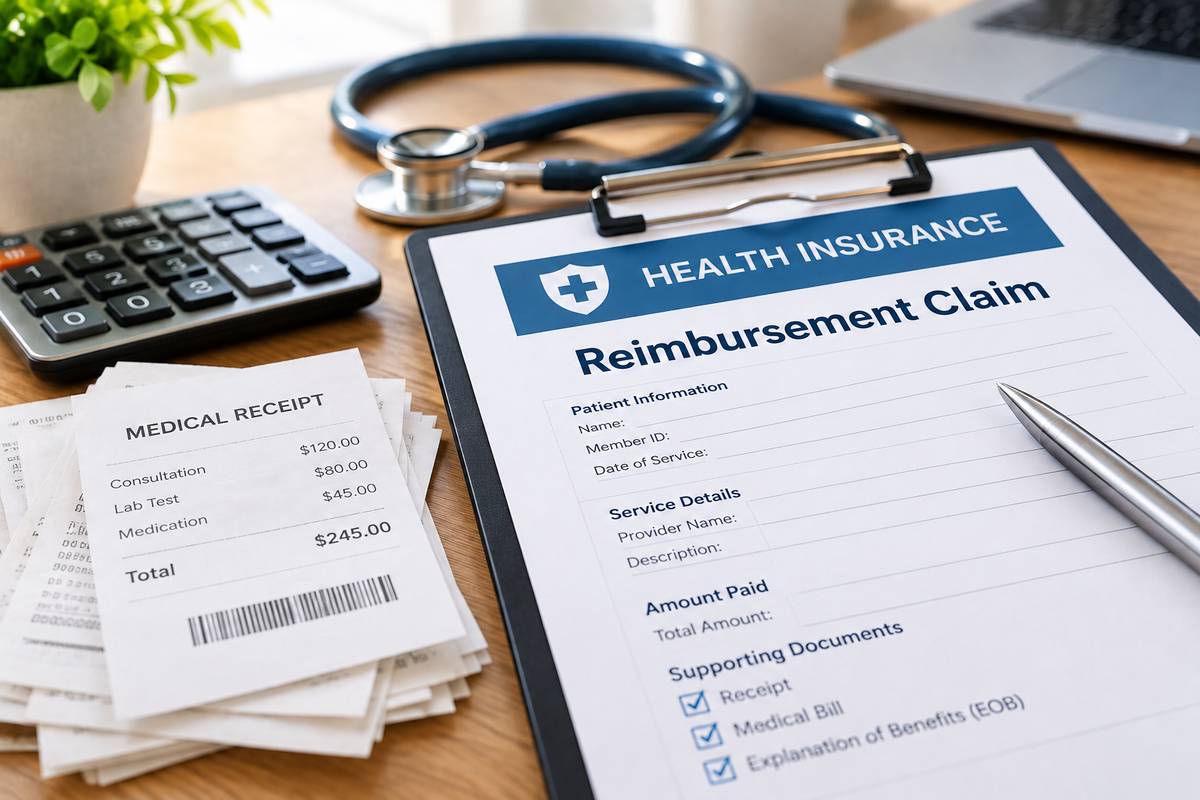
A reimbursement claim is a request asking your insurance company to repay you for an eligible healthcare expense you paid directly.
When you receive services from NHWS, you pay the clinic directly. If your plan offers applicable out-of-network benefits, you can ask your insurer how to submit your superbill and request reimbursement. Any reimbursement is determined by your insurance plan and insurer.
Other Important Health Insurance Terms
What is a provider network?
A provider network is the group of healthcare professionals and facilities that have contracts with an insurance company to provide services under agreed terms.
In-network providers generally have contracted rates. Out-of-network providers do not have the same contractual relationship with your plan.
What are covered services?
Covered services are services your insurance plan includes as eligible benefits, subject to the plan’s conditions and limitations.
A service being covered in general does not necessarily mean your insurer will pay for it when you receive it.
What is prior authorization?
Prior authorization, also called preauthorization or precertification, is a review by your insurer to determine whether a proposed service meets its requirements before you receive care.
Some plans require prior authorization for occupational therapy or mental health services, including certain out-of-network services.
Authorization is not a guarantee of reimbursement. Confirm both the authorization requirements and the payment rules with your insurer.
What is an Explanation of Benefits (EOB)?
An Explanation of Benefits, or EOB, is a statement from your insurance company explaining how it processed a claim.
It may show the amount submitted, the allowed amount, any amount the insurer paid, and your responsibility under the plan.
An EOB is not a bill. Review it to understand how your insurer processed a claim and whether you need to provide additional information.
What is a claim denial and appeal?
A claim denial occurs when an insurer declines to pay all or part of a submitted claim.
Reasons may include lack of coverage, unmet requirements, missing information, or a service that does not meet the plan’s criteria.
If your insurer denies reimbursement, ask for the reason in writing and find out whether you can appeal the decision.
Why Choose an Out-of-Network Therapy Provider?
Insurance coverage is an important consideration when choosing a healthcare provider. Some people prefer in-network care because it can reduce their out-of-pocket costs. Others choose an out-of-network provider because the provider’s services, availability, approach, or specialization better fit their needs.
At New Horizons Wellness Services, our private-pay model allows our clinicians to develop care around each client’s goals without relying on an insurance company’s visit limits or authorization decisions to determine the course of treatment.
Our services include occupational therapy for children and adults, social skills programs, psychological evaluations, and counseling.
Depending on the service and your needs, care may address areas such as:
● ADHD and executive functioning
● Sensory processing and self-regulation
● Handwriting and fine motor skills
● Daily living, school, work, and social participation
● Psychological assessment and mental health needs
Diagnosis Requirements
Insurers typically require a formal mental health or medical diagnosis code to approve and pay for services. This means even if you’re seeking support for everyday stress, communication skills, or developmental progress rather than a diagnosable condition, your provider may need to assign a diagnosis just to bill your insurance, and that diagnosis becomes part of the health information associated with your insurance claim and medical records.
Medical Necessity Limits
Insurance companies decide what counts as “medically necessary,” not you and your provider. That can mean limits on the number of covered sessions, restrictions on which treatment approaches are approved, or a requirement to demonstrate ongoing “progress” in a specific, insurer-defined way, even when a client would benefit from continued, steady support.
Privacy Considerations
Every claim submitted to insurance passes through your insurer’s systems, and in some cases, employer-sponsored plans, which means details about your care may be more visible than you’d expect. Paying privately can limit the health information that needs to be shared with an insurance company
Flexibility in Care
Without insurance restrictions, you and your provider can determine the frequency, length, and type of treatment that actually fits your goals, rather than what a plan is willing to authorize.
For many people, the amount that they end up paying out of network is similar to what they will pay for in network services. By understanding that private-pay options exist and may be worth exploring depending on your priorities many people find that they have more options for care. .
How to Check Your Out-of-Network Benefits
Contact the member services number on your insurance card. Ask about the specific service you are considering, rather than asking only whether your plan has out-of-network benefits.
Use these questions as a starting point:
- Does my plan cover out-of-network occupational therapy or psycholocal services? Ask about the exact service and provider type.
- What is my out-of-network deductible? How much have I met, and is it separate from my in-network deductible?
- What is my out-of-network reimbursement rate? Ask how the insurer calculates the allowed amount and its payment percentage.
- Does my plan require prior authorization or a referral? Ask what must be completed before the first visit.
- How do I submit a superbill? Find out which forms, codes, and supporting documents are required.
- How will reimbursement be paid to me? Ask how payments are issued when you pay the provider directly.
- Do out-of-network expenses count toward my out-of-pocket maximum? Ask whether a separate maximum applies.
- Are there visit limits or other restrictions? Ask whether the plan limits the number, type, or duration of covered sessions.
Keep a record of the information you receive, including the date of the call and any reference number. Request written confirmation when possible.
Remember that a benefits estimate or authorization is not necessarily a guarantee that a claim will be paid.
Understand Your Options
You do not need to understand every insurance term to make a good decision about healthcare. Start by identifying the benefits that apply to the service you need, confirming your financial responsibilities, and learning how reimbursement works. For services like counseling and occupational therapy, the right choice often depends on your specific goals, privacy preferences, and how much flexibility you want in your treatment.
At New Horizons Wellness Services, we provide occupational therapy for children and adults, social skills programs, psychological evaluations, and counseling. Our team can explain our private-pay process and provide a superbill for possible insurance reimbursement.
We offer in-person services in Beaverton, Oregon, and telehealth for eligible services throughout Oregon.
Ready to learn more about services at NHWS?
Visit nhws.us or call 503-352-0240 to discuss your needs and next steps. Book a call now!
Frequently Asked Questions About Insurance and Out-of-Network Therapy
Does New Horizons Wellness Services accept insurance?
New Horizons Wellness Services is an out-of-network, private-pay provider. We do not directly bill commercial insurance companies. We can provide a superbill for you to submit to your insurer for possible reimbursement, depending on your plan.
Can I get reimbursed for occupational therapy at NHWS?
Possibly. Reimbursement depends on your insurance plan, the service provided, applicable deductibles and coinsurance, authorization requirements, and other coverage rules. Contact your insurer before starting care to confirm your benefits.
What is the difference between a copay and coinsurance?
A copay is a fixed dollar amount you pay for a covered service. Coinsurance is a percentage of the amount your plan recognizes for a covered service.
Do I have to meet my deductible before insurance reimburses me?
It depends on your plan. Some plans require you to meet a deductible before they contribute to eligible services. Others may apply different cost-sharing rules. Ask your insurer which requirements apply to your service.
Why would a provider need to give me a diagnosis to bill insurance?
Insurance companies require a diagnosis code to determine medical necessity and process a claim, even for services like therapy where the client may not consider themselves to have a diagnosable condition.
What is the difference between private pay and out-of-network care?
Private pay means you pay the provider directly rather than having the provider bill your insurer. Out of network describes the provider’s relationship with your insurance plan.
At NHWS, clients pay for services directly. If their plan offers applicable out-of-network benefits, they may submit a superbill and request reimbursement.
Is private-pay therapy more expensive than using insurance?
The answer depends on your plan, deductible, coinsurance, reimbursement rules, and the provider’s fee. Compare the total amount you expect to pay, not just the copay listed on your insurance card. The total cost can sometimes be comparable, especially when you factor in flexibility around session frequency and treatment approach.
Additional Resources
For official information about health insurance terminology, visit:
- HealthCare.gov: Glossary of Health Coverage and Medical Terms
- U.S. Department of Labor: Summary of Benefits and Coverage resources
This article is for general educational purposes. It is not insurance, legal, or financial advice. Insurance benefits and reimbursement rules vary by plan. Contact your insurer to confirm coverage and payment requirements for your specific services.
Yours in Health,
New Horizons Wellness Services8880 SW Nimbus Ave Suite C.,
Beaverton, OR 97008
- https://g.page/newhws
New Horizons Wellness Services provides a true multidisciplinary approach to mental & physical health treatments for children, adults and families.